
To those only vaguely familiar with the opaque world of fundraising, a “Term Sheet” is a sort of mythical creature that exists in startup land. They come around once in a while, usually linked to fantastic stories of overnight riches, or baked into the plot of a TV series. But for outsiders, it’s hard to describe what they actually look like, or even confirm if they are a real thing. Kind of like a Narwhal.

1/3 of people stopped reading by now. Also, ya boy copped a Canva sub. Get at me.
So what does a VC Term Sheet actually look like? How are they structured? What are the key “Terms?” And what’s a “dirty” term sheet?
What’s a Term Sheet
A term sheet is a nonbinding document outlining the price and conditions of a private investment. It serves as a template and the basis for more detailed, legally binding documents. It’s basically a non formal version of a formal process that might go down. It shows commitment without really committing.

And, if startups are really special, they may receive multiple term sheets at the same time from various investors and get to choose one. This often happens in high demand rounds, like what we saw from 2021 through 2022.

“You get a term sheet, you get a term sheet, you…”
What does a term sheet look like?

Source: Y combinator
The structure
Offering Terms: Includes the closing date, investor names, amount raised, the price per share and pre-money valuation. It’s a summary up front of the who, what, where, and when.
Charter: The charter shows the dividend policy, liquidation preferences, protective provisions, and pay to play provisions. That’s a lot of jargon, so think of this section as an outline for how things should go after the deal goes down, and who gets what upon another round / M&A event / catastrophic failure. We’ll break down some of these terms down below.
Stock Purchase Agreement (“SPA”): A stock purchase agreement outlines the sale of company stock to buyers. Stock purchase agreements are common among small corporations; they provide capital while allowing the business owner to retain a controlling interest. It’s basically how you sell shares in a company when you are not public. You’ll find the following details in an SPA:
The company’s name
The name and mailing address of the entity buying shares
The par value (essentially the sale price) of the stocks being sold
The number of stocks the buyer is purchasing
The transaction’s date, time and location
Seller and buyer warranties and representations
Bonuses, benefits and other potential employee issues
An indemnification clause to address unexpected costs
Investor Rights: This outlines what information investors are entitled to receiving on a regular basis, if they get to participate before other investors in future rounds, how long they’d have to wait before selling upon an IPO, and other stuff to keep them in the loop and guard their downside.
Right of First Refusal: This outlines who gets first dibs on any shares that existing shareholders want to offload, before anyone else can scoop them up.
Voting Agreement: This outlines who’s on the board and gets to vote on issues, like approving the annual operating plan, and how drag along rights work (more on that below).
The lingo
Information Rights: Makes sure preferred shareholders get a copy of quarterly and annual financials. This allows investors to keep tabs on company performance. They get this info even if they aren’t on the board of directors or have an observer seat at board meetings.
Right to Participate: Existing investors have the right to buy shares offered in subsequent financing rounds. That means when another round is raised, they’ll have a seat at the table (if they want it).
Pro Rata Rights: Allows an investor to maintain their initial level of ownership percentage during later financing rounds by purchasing more shares. When a company raises a round, new shares are created and shareholders mathematically will get diluted. This feature prevents dilution, allowing investors to purchase more shares to keep the same ratio.
Employee Option Pool: This is the percentage of stock that must be put aside and reserved for key employees. The majority of it will go to new hires, and some will be used to top up existing employees who have been onboard for a while. This is important to establish so the company can attract new talent, and crucial to specify the shape and size so investors don't get more diluted if the pool runs out.
Pre Money Valuation: The valuation investors agree a company is worth before money is injected into the business.
Post Money Valuation: The Pre money valuation plus the amount of capital that is raised and now sits on the balance sheet.
Drag Along Rights: All shareholders must sell if the board and/or a majority of shareholders approve. This is important so deals don't get held up. Although there are two of us in the relationship, my wife has super voting rights and I get dragged along to a lot of neighborhood parties I don’t want to go to.
Liquidation Preference: Who gets paid out first? Investors want to know the order in which owners are paid out in the event the company gets sold (or goes out of business). All things equal, you want to be first in line, because if the company sells for less than it’s valuation, someone will be left hanging. It could be a long line, and you want to be up front before they run out of whatever cash they are serving. This feature is important to investors as it reduces investment risk.
Preferred Shares: Investors who get paid first hold "preferred" shares, which are theoretically worth more than "common" shares. They also may get different voting rights. This is where the phrase “Pref” comes from.
No-Shop Agreement: This is so a company doesn’t leverage one investor’s term sheet to get a better one. Investor’s don’t like to feel used, so this gives them an “exclusive” and finite block of time for investors to decide if they want to accept their term sheet and start getting serious.
What to watch out for
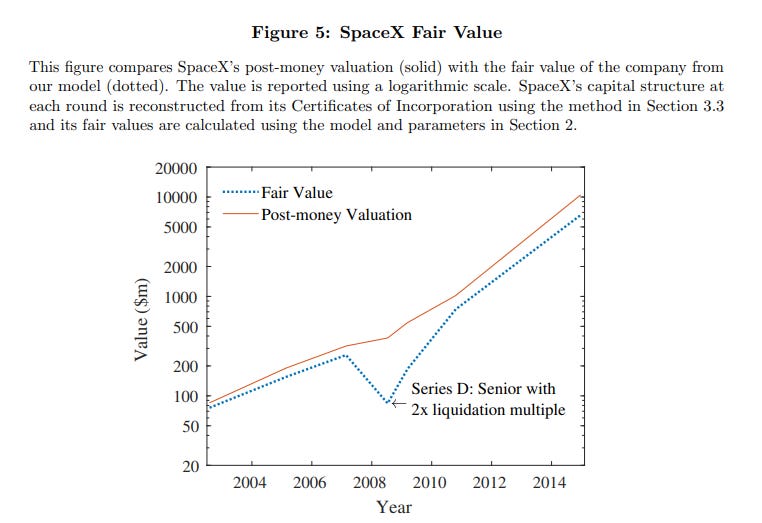
When a term sheet has “structure” to it, that’s a polite way of saying it’s “dirty”.
A dirty term sheet benefits certain VCs over over the founders and employees (and maybe even earlier VCs on the cap table). It includes provisions to safeguard their downside, usually in exchange for a higher valuation.
Dirty term sheets usually rear their ugly heads when the company is attempting to preserve a past valuation, and not accept the reality of a “down round”. The result is asymmetric risk allocation, where people end up with varying incentives depending on what they have to lose. did an excellent job breaking down the varying levels of “dirty” and the implications of accepting a “ticking time bomb”.
Red flags
In general, watch out for these five red flags:
Anything above a 1x liquidation multiplier
You don’t want your pref stack as tall as Shaq
Otherwise you risk the founders and employees not getting paid, even if it’s a “good” exit - it sucks when only some people get to high five
Super pro rata rights
Pro rata rights are designed to protect investors from dilution in subsequent rounds
Super pro-rata rights guarantee an investor the ability to demand more than their initial investment in ensuing rounds
For instance, say a VC owns 10 percent of your company after the B round, and has super pro rata rights for up to 25% if you do a Series C round
This might scare off future investors and make fundraising hard, as it leaves limited room for net new investors
Full-ratchet price-based anti-dilution provisions
“Too dirrty to clean my act up” (IYKYK)
Aggressive turn around times before the term sheet expires
You should minimally have 7 business days to consider it
Otherwise it signals the VC is not confident in their ability to win allocation on their own merits, or they know it’s a bad deal
At the same time, it’s fully in the VCs right to make sure you don’t have too long to go and shop it; that’s not fair either
Converting common stock purchased in a parallel secondary transaction into preferred shares
This benefits the early employees and investors selling their stock, since they get a higher price for their common shares (usually the same price as the Series [x] preferred shares, rather than taking a ~20% discount)
It also benefits the new round’s investors who get to suck up more preferred stock than they would have gotten in the primary
But it disadvantages everyone else on the cap table
Existing investors now have proportionally less voting rights, need to achieve a higher valuation to make sure the pref stack doesn’t overwhelm them, and the business isn’t getting any additional cash to go out and make magic
Smart Stuff I Read at 2AM:
What a term sheet looks like - Y Combinator
What is a term sheet - Wall Street Prep
What is an SPA - Business.com
Watch out for these terms - Carta
What are super pro rata rights - Open View
Why Super Pro-rata Rights are Not a Good Deal for Entrepreneurs - Mark Suster
Quote I’ve been pondering:
“What's the point of being an outlaw when you got responsibilities?”
-Jesse Pinkman, Breaking Bad
Mostly archives
FP&A F’ Ups - a list of FP&A boobytraps
How much dilution is normal - measuring typical dilution through the rounds
Never let a good crisis go to waste - what’s really happening with the tech layoffs


